Macroeconomic forces dictate the flow of global capital before individual token fundamentals ever come into play. Global liquidity drives the crypto market. When liquidity dries up, buyers disappear. Even the most innovative decentralized applications struggle to attract capital.
The opposite happens when central banks ease monetary policy. New money enters the financial system. As that liquidity spreads, digital assets rise with the tide, regardless of sector-specific noise.
For years, crypto traders operated inside a self-contained sandbox, relying almost exclusively on chart patterns and on-chain metrics.
Today, institutional participation, spot exchange-traded funds, and global regulatory frameworks like EU MiCA have fused cryptocurrency directly into the nervous system of global finance.
To build durable wealth across multi-year market cycles, every market participant must understand the fifteen primary macroeconomic gauges that steer capital toward or away from digital assets.
Macro indicators in cryptocurrency research are high-level economic statistics and financial market metrics used to measure systemic liquidity, sovereign interest rate policy, currency strength, and global investor risk tolerance.
Because cryptocurrencies function as highly sensitive, high-beta liquidity gauges, their valuations rise during periods of monetary expansion and fall sharply when central banks restrict credit.
Tracking macro indicators allows researchers, traders, and institutional allocators to determine whether crypto market fluctuations stem from industry-specific catalysts or worldwide monetary tides.
ZenvestAI Quick Insight
Traditional equity markets react to economic news with quarterly earnings revisions, but digital assets price sovereign monetary decisions in real time.
Global liquidity acts as the tide that lifts or grounds all boats; individual cryptocurrencies merely decide which boat has the best sails. If you misjudge the tide, even the finest vessel will get stranded on the reef.
Key Takeaways
- Liquidity reigns supreme: Global money supply (M2) and central bank balance sheets serve as the primary drivers of secular crypto market expansions.
- The Dollar dictates capital flows: The US Dollar Index (DXY) maintains a persistent historical inverse correlation with digital asset valuations, acting as an international financial tightening gauge.
- Cost of capital sets the ceiling: Real interest rates (yields adjusted for inflation) define the baseline return investors can capture risk-free, determining the premium required to hold digital assets.
- Institutional gateways alter market structure: Spot crypto ETF flows and stablecoin market capitalizations now bridge traditional fiat balance sheets directly with distributed ledgers.
- Cross-asset stress signals market turns: Widening corporate credit spreads and sharp spikes in bond volatility reliably warn of broad deleveraging events before they hit crypto exchanges.
At a Glance
| Indicator | Primary Economic Driver | Direct Impact on Crypto | Typical Market Lead Time |
| Global M2 Money Supply | Global Central Bank Money Creation | Bullish when expanding; Bearish when contracting | 8 to 12 weeks |
| US Dollar Index (DXY) | FX Liquidity & Global Capital Safety | Bullish when falling; Bearish when rallying | Real-time to 2 weeks |
| Real Treasury Yields (TIPS) | Global Real Cost of Capital | Bullish when declining; Bearish when rising | 1 to 4 weeks |
| Fed Net Liquidity | Domestic Banking Reserve Availability | Direct positive correlation with Bitcoin price | Real-time to 1 week |
| High-Yield Credit Spreads | Corporate Default Risk & Debt Health | Bullish when narrowing; Bearish when widening | Real-time warning |
| Yield Curve Spread (10Y–2Y) | Economic Growth & Recession Odds | Bullish during steepening from cuts; volatile on steepening from panic | 3 to 6 months |
| US Consumer Price Index (CPI) | Inflationary Pressures & Rate Paths | Volatile short-term; Bullish if disinflation enables rate cuts | Real-time reaction |
| Global Central Bank Policy Rates | Worldwide Monetary Policy Stance | Bullish during synchronized easing cycles | 1 to 3 months |
| CBOE Volatility Index (VIX) | Equity Market Fear & Deleveraging | Bearish spikes force portfolio liquidation | Immediate |
| Gold to S&P 500 Ratio | Defensive Hedging vs. Risk Appetite | Signals risk-off rotation when spiking upward | 2 to 4 weeks |
| Commodity & Energy Prices | Cost-Push Inflation Pressures | High energy costs pressure miner margins and tighten policy | 4 to 8 weeks |
| Stablecoin Supply Dynamics | Native Digital Market Dry Powder | Expanding stablecoin float fuels crypto purchasing power | Leading indicator |
| Spot ETF Net Capital Flows | Traditional Institutional Capital Access | Direct institutional buy/sell pressure on spot markets | Daily execution |
| Global Manufacturing PMI | Worldwide Real Economic Expansion | Expansion above 50 supports consumer and speculative risk | 1 to 2 months |
| ON RRP & TGA Operations | Direct Dollar Buffers in Treasury & Fed | Balance depletion releases liquidity into private markets | Real-time |
15 Macro Indicators for Crypto Research: A Practical Guide
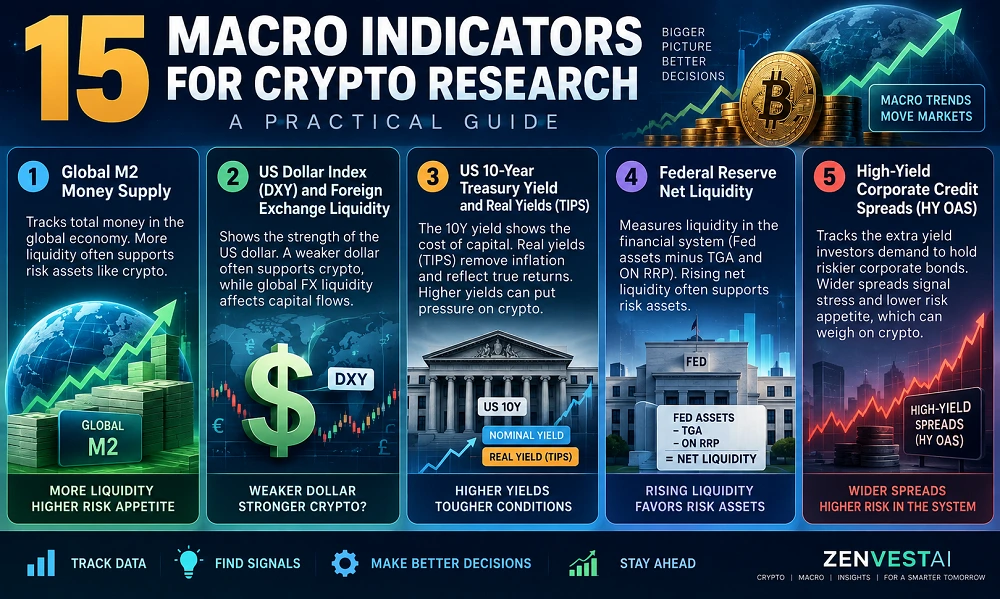
Table of Contents
- Why Macro Matters More Than Ever for Crypto
- How Macro Shocks Propagate Through Digital Asset Markets
- The 15 Core Macro Indicators for Crypto Research
- Risks and Analytical Limitations of Macro Modeling
- Institutional and Regulatory Impact on Market Behavior
- Practical Application: Building a Weekly Macro Research Routine
- Traditional Metrics Versus Crypto-Native Indicators
- The Next Evolution of Digital Asset Macroeconomics
- Frequently Asked Questions
- ZenvestAI View
- The Bottom Line
- Related Intelligence
- Author and Editorial Information
- Regulatory Compliance and Analytical Disclosure
Why Macro Matters More Than Ever for Crypto
Digital assets no longer trade in technological isolation. During Bitcoin’s first decade, price action was primarily governed by halving cycles, developer milestones, retail speculation, and occasional exchange insolvencies.
Over the past several market cycles, sovereign wealth vehicles, multi-strategy hedge funds, public corporations, and regulated asset managers entered the ecosystem, integrating digital currencies into standard asset allocation frameworks.
The Great Institutional Convergence
Institutional capital allocates according to portfolio mandates, risk budgeting, and liquidity requirements. When macroeconomic indicators trigger a risk-off alert in traditional finance desks, portfolio managers rebalance across all asset classes simultaneously.
They do not exempt cryptocurrencies from liquidations simply because of strong on-chain network activity.
This transformation means that a sudden liquidity squeeze in London or a policy adjustment in Tokyo reverberates through crypto derivatives markets within seconds.
Understanding macroeconomics is therefore no longer an academic exercise; it is an essential defense against unexpected portfolio drawdowns.
Why Digital Assets Function as High-Beta Liquidity Sponges
Cryptocurrencies carry no sovereign debt backing, offer no legal claims on physical manufacturing machinery, and possess variable cash flows.
Because of these distinct attributes, the market prices digital assets based on future adoption expectations, monetary debasement insurance, and available systemic liquidity.
When fiat currencies lose purchasing power due to central bank balance sheet expansion, digital assets absorb excess liquidity rapidly.
Conversely, when sovereign central banks restrict liquidity to fight consumer inflation, speculative capital flees the outer risk curve first.
Crypto sits at the furthest frontier of that risk curve.
From Market Structure to Capital Transmission
Knowing that crypto acts as a financial sponge raises an immediate question: through what practical plumbing does a change in macroeconomic policy actually move prices on a decentralized exchange or order book?
How Macro Shocks Propagate Through Digital Asset Markets
Macroeconomic adjustments do not influence crypto prices by magic; they travel through four primary market channels.
First is the margin and leverage channel. When borrowing benchmarks rise, the interest rates charged on crypto perpetual futures, broker margin loans, and decentralized finance lending protocols rise in tandem. Higher funding expenses force leveraged traders to close positions, reducing aggregate market depth.
Second is the institutional portfolio rebalancing channel. Institutional mandates typically enforce strict volatility caps and value-at-risk limits. If cross-asset volatility spikes across government bond markets, quantitative algorithms automatically trim high-volatility holdings, including Bitcoin and Ethereum, to bring fund risk metrics back into compliance.
Third is the foreign exchange and international trade channel. International trade is overwhelmingly conducted in fiat currencies, primarily the US Dollar. When foreign currencies depreciate against the greenback, international corporations face tighter cash constraints, reducing speculative capital pools in Asia, Europe, and Latin America.
Fourth is the opportunity cost channel. When a government bond provides a safe nominal yield of 4% to 5%, capital allocators demand a substantially higher hurdle rate to justify staking coins or financing crypto venture networks.
Now that we understand how monetary shifts travel through financial pipes into digital assets, we must isolate the specific gauges that provide early warnings of these capital shifts.
The 15 Core Macro Indicators for Crypto Research
1. Global M2 Money Supply
Global M2 money supply measures the aggregate volume of cash, checking accounts, savings deposits, and liquid money market balances held across the world’s leading economies.
Researchers aggregate data from the US Federal Reserve, the European Central Bank, the People’s Bank of China, and the Bank of Japan to build a unified global liquidity tracker.
Historically, rapid accelerations in global M2 growth precede major crypto bull markets, while sharp decelerations or outright contractions align with severe multi-quarter bear markets.
Empirical research from institutional analytics platforms such as CF Benchmarks reveals that changes in global M2 money supply typically lead Bitcoin price inflections by approximately eight to twelve weeks.
When broad money supply across the top central banks expands at an annualized pace exceeding historical norms, the capital surplus invariably spills into alternative non-sovereign stores of value.
2. US Dollar Index (DXY) and Foreign Exchange Liquidity
The US Dollar Index (DXY) measures the valuation of the US Dollar relative to a basket of key foreign currencies, including the Euro, Japanese Yen, British Pound, and Canadian Dollar.
Because the US Dollar serves as the dominant global reserve currency and the quoting denomination for international commodities and crypto trades, a strengthening dollar represents a global credit tightening event.
When the greenback appreciates, non-US entities find it far more costly to service dollar-denominated debts, pulling capital out of risky investments to secure cash reserves.
Tracking the rolling 30-day and 90-day correlation between the DXY and Bitcoin on data portals like MacroMicro shows an enduring inverse relationship.
Parabolic crypto advances almost exclusively take place during structural downtrends in the DXY, whereas rapid dollar short squeezes reliably trigger broad crypto pullbacks.
3. US 10-Year Treasury Yield and Real Yields (TIPS)
The yield on the benchmark 10-Year US Treasury note represents the base discount rate for the global financial ecosystem, but real yields provide the truest measure of financial conditions.
Nominal yields reflect both expected economic growth and inflation expectations. To calculate the real yield, subtract expected inflation from the nominal yield, a figure directly observed through 10-Year Treasury Inflation-Protected Securities (TIPS).
When real yields drop into negative territory, cash and sovereign debt guarantee a loss in real purchasing power over time. Under negative real yield regimes, institutional investors actively hunt for alternative scarce assets, creating an ideal macro environment for digital assets.
Conversely, when real yields climb toward multi-decade highs, holding sovereign paper becomes highly attractive, dampening the urgency to hold non-yielding or volatile assets.
4. Federal Reserve Net Liquidity
The headline size of the Federal Reserve’s balance sheet alone does not tell you how much usable money is circulating in the commercial financial system. Federal Reserve Net Liquidity refines the central bank’s balance sheet by subtracting statutory liabilities that hold cash inactive.
The operational formula used by institutional analysts on StreetStats is:
Cash parked in the Treasury General Account (the US government’s checking account) or locked inside the Overnight Reverse Repo facility cannot circulate in commercial credit channels.
When the Fed cuts total assets through Quantitative Tightening (QT), but cash drains out of the ON RRP facility back into commercial banks, Net Liquidity can actually rise.
Digital asset prices consistently track this calculated Net Liquidity figure with far greater precision than the raw Federal Reserve balance sheet.
5. High-Yield Corporate Credit Spreads (HY OAS)
The Option-Adjusted Spread (OAS) on high-yield corporate bonds measures the premium that sub-investment-grade companies must pay to borrow money compared to risk-free US Treasuries.
Credit markets are populated by sophisticated institutional debt specialists who scrutinize corporate cash flows and balance sheets. Consequently, credit spreads widen well before equity or crypto traders identify systemic insolvency risks.
When high-yield credit spreads remain narrow and compressed, access to corporate credit is abundant, reflecting high lender confidence and robust risk appetite.
However, if credit spreads widen rapidly by more than 100 basis points over a short window, it warns that debt refinancing pipelines are seizing up.
In every major liquidity panic over the past two decades, widening credit spreads forced margin calls and liquidations across digital asset exchanges.
6. Treasury Yield Curve Slopes (10Y–2Y and 10Y–3M)
The slope of the Treasury yield curve reflects bond investor expectations regarding economic growth, monetary policy, and credit conditions.
Under healthy economic conditions, longer-term bonds pay higher yields than short-term bills to compensate for duration risk, creating an upward-sloping curve. When short-term yields exceed long-term yields, the curve becomes inverted, serving as a reliable historical harbinger of economic recessions.
For crypto research, the most critical moment is not the initial curve inversion, but the subsequent uninversion and re-steepening.
When an inverted curve re-steepens because short-term yields collapse in anticipation of emergency central bank rate cuts (a “bull steepener”), it typically indicates that economic distress has arrived.
Crypto markets frequently experience substantial volatility during these transition periods before finding a sustainable floor once monetary easing begins in earnest.
7. Consumer Price Index (CPI) and Core Inflation Momentum
The Consumer Price Index (CPI) measures changes in the price level of a market basket of consumer goods and services purchased by households.
Central banks manage statutory mandates centered on price stability. When CPI prints run uncomfortably hot above central bank targets (such as the Federal Reserve’s 2% benchmark), monetary officials are forced to maintain restrictive policy rates or accelerate quantitative tightening.
While Bitcoin was historically celebrated as an instant inflation hedge, empirical market behavior reveals that high headline CPI prints often produce immediate downward price pressure on crypto.
This occurs because the market immediately prices in a more aggressive, hawkish response from central bank rate-setters.
Sustainable digital asset appreciation generally flourishes during disinflationary regimes, where slowing inflation metrics give central bankers permission to lower borrowing costs.
8. Central Bank Policy Rate Trajectories
Central bank policy rates, such as the Federal Funds target rate, dictate the overnight cost of uncollateralized lending among commercial banks.
A coordinated global rate-cutting cycle fundamentally reshapes the global cost of capital. When major central banks—including the Federal Reserve, the European Central Bank, the Bank of Japan, and the People’s Bank of China—simultaneously ease policy, fiat currency yields diminish across the board.
Investors should monitor interest rate futures and forward overnight index swaps to gauge market expectations rather than focusing purely on past rate decisions. Markets trade on the gap between current policy and future expectations.
When central banks ease policy more aggressively than market forward pricing expects, speculative risk assets, spearheaded by major cryptocurrencies, typically stage rapid upward revaluations.
9. CBOE Volatility Index (VIX) and Cross-Asset Volatility
The CBOE Volatility Index (VIX) calculates the market’s expectation of 30-day forward-looking volatility derived from S&P 500 index options.
The VIX is widely referred to as the market’s fear gauge. Because cross-market risk algorithms evaluate equity volatility to determine permissible portfolio leverage, sustained readings above 30 indicate widespread panic, forced deleveraging, and broad liquidity conservation.
During sharp VIX spikes, automated trading desks liquidate profitable or liquid positions to satisfy collateral obligations in derivative accounts. Digital assets, which trade 24 hours a day, 7 days a week, often bear the immediate brunt of these collateral calls during weekend or overnight hours when traditional exchanges are closed.
Monitoring the VIX alongside dedicated crypto volatility indices (such as the Volmex BVIV or DVOL) helps identify whether a crypto pullback is an idiosyncratic event or part of a systemic multi-asset sell-off.
10. Gold-to-S&P 500 Ratio
The Gold-to-S&P 500 ratio compares the relative market performance of a non-yielding physical monetary store of value against the equity shares of productive, cash-generating corporations.
A rising ratio signals that capital allocators are prioritizing defensive balance sheet preservation over operational economic expansion. When this ratio trends upward persistently, institutional risk appetite is waning, creating a challenging backdrop for altcoins and speculative crypto tokens.
Conversely, when the Gold-to-S&P 500 ratio is declining, capital is rotating out of defensive havens and into risk assets.
Bitcoin occasionally diverges from equities to track gold during sovereign banking panics (as observed during the US regional banking crisis in March 2023). However, broader cryptocurrency markets thrive most reliably when general risk appetite is robust and defensive gold allocations are stabilizing.
11. Commodity and Energy Benchmarks
Commodity indices and energy benchmarks, particularly Brent Crude Oil and copper, reflect real-world supply-demand fundamentals and industrial momentum.
Crude oil acts as a fundamental input cost for global transportation, manufacturing, and agricultural production. Sudden spikes in energy prices introduce cost-push inflation, complicating monetary policy by constraining consumer discretionary spending while preventing central banks from lowering rates.
Additionally, industrial commodities like copper (“Dr. Copper”) provide a real-time health check on worldwide infrastructure spending and manufacturing activity. In crypto-native operations, electricity prices directly determine the operational profitability of proof-of-work mining operations.
When energy costs escalate while cryptocurrency prices consolidate, distressed miners are frequently forced to liquidate their coin reserves to cover operational overhead, creating structural spot market selling pressure.
12. Stablecoin Supply Dynamics and Velocity
Total circulating stablecoin supply represents the dedicated, liquid purchasing power standing on crypto-native rails.
Unlike fiat currency parked in traditional commercial checking accounts, stablecoins such as Tether (USDT) and USD Coin (USDC) sit directly on public distributed ledgers, ready to execute trades within seconds.
Tracking aggregate stablecoin market capitalization on aggregators such as DefiLlama provides a direct view into whether net fiat capital is entering or departing the blockchain ecosystem.
When aggregate stablecoin supply is expanding steadily, it confirms that new fiat capital is being tokenized and deployed to exchange reserves and on-chain liquidity pools.
Conversely, when stablecoin market capitalization contracts over consecutive months, it reveals that investors are redeeming digital dollars for traditional banking deposits, directly draining liquidity from the crypto ecosystem.
13. Spot Crypto ETF Net Capital Flows
The launch and maturation of regulated spot crypto ETFs in the United States and global financial centers created a direct conduit between multi-trillion-dollar wealth management platforms and spot digital assets.
Data aggregators like Farside Investors and CoinGlass track these metrics daily. Institutional investors, registered investment advisors (RIAs), and retirement funds that face strict charter restrictions against managing private cryptographic keys now execute their exposure through spot ETF shares.
Sustained multi-week net inflows into spot ETFs generate steady, inelastic structural demand, as authorized participants must purchase and deposit physical spot tokens into custody accounts.
Conversely, persistent daily net outflows signal institutional de-risking, creating continuous selling volume that can overwhelm retail bids during broader market pullbacks.
14. Global Manufacturing Purchasing Managers’ Index (PMI)
The Purchasing Managers’ Index (PMI) is an economic indicator based on monthly surveys of private-sector supply chain executives across global manufacturing and service industries.
A headline PMI reading above 50 indicates expansion in economic activity compared to the prior month, while a reading below 50 signals contraction. Tracking the global composite PMI compiled by S&P Global and the Institute for Supply Management (ISM) offers an early look at worldwide corporate revenues and industrial demand.
Digital assets demonstrate a pronounced positive correlation with global manufacturing cycles. When the global manufacturing PMI rebounds from sub-48 contractionary territory and crosses back above the 50 expansion threshold, corporate earnings improve, credit conditions normalize, and discretionary capital pools expand.
This environment creates favorable economic conditions that support extended crypto bull market runs.
15. Overnight Reverse Repo (ON RRP) and Treasury General Account (TGA) Operations
The liquidity balance held at the Federal Reserve’s Overnight Reverse Repurchase Facility (ON RRP) and the balance of the US Treasury General Account (TGA) represent two critical liquidity buffers within the US Dollar system.
When the US Treasury issues new debt to replenish the TGA, it absorbs cash from private financial markets unless that issuance is absorbed by money market funds drawing down balances out of the ON RRP.
When money market funds pull cash out of the ON RRP facility to purchase newly issued short-term Treasury bills, broad private market liquidity remains insulated from Treasury borrowing.
However, once the ON RRP facility is exhausted, every dollar of new Treasury debt issued must be funded directly from commercial bank reserves. This drains private liquidity and introduces significant downward pressure on risk assets, including cryptocurrencies.
Having assembled our fifteen-indicator macro dashboard, we must avoid the common mistake of treating these metrics as flawless mechanical trading signals.
Risks and Analytical Limitations of Macro Modeling
Macroeconomic indicators provide essential structural context, but they do not eliminate market uncertainty. Applying macro models carelessly to crypto research introduces distinct analytical risks that can distort decision-making.
The first major hazard is the lag trap. Headline government statistics like GDP and employment reports are backward-looking indicators; they describe economic conditions that occurred weeks or months prior. Financial markets trade on forward expectations.
If an investor sells digital assets simply because a backward-looking economic report prints weak data, they risk dumping positions precisely when forward-looking liquidity has already bottomed.
The second pitfall is temporary correlation breakdowns. Relationships between macroeconomic variables and digital assets are dynamic rather than fixed constants.
For instance, while the US Dollar Index and Bitcoin generally move in opposite directions, there are market phases where both assets appreciate simultaneously due to intense geopolitical flight-to-safety flows. Assuming that an inverse correlation will hold true on every single trading day leads to poor trade execution and flawed risk modeling.
The third pitfall is crypto-native narrative overrides. Macroeconomic liquidity establishes the playing field, but native industry events can temporarily overpower macro trends.
The collapse of a major custodial exchange, a multi-billion-dollar protocol exploit, an abrupt regulatory enforcement action, or a scheduled network upgrade can trigger sharp independent market moves. A pristine macro backdrop cannot shield an asset from severe structural damage caused by internal protocol failures.
Understanding the Institutional Arena
Beyond raw data and potential analytical pitfalls, macro indicators now operate inside an evolving institutional landscape defined by sovereign regulations and corporate investment committees.
Institutional and Regulatory Impact on Market Behavior
Institutional adoption has permanently reshaped how macroeconomic data influences cryptocurrency pricing. Prior to the entry of regulated custodians and corporate balance sheets, crypto was traded largely by retail participants on offshore exchanges with opaque liquidity pools. Today, capital allocators operate under rigorous governance frameworks.
The Role of Global Regulatory Frameworks
Regulatory clarity across key financial jurisdictions has transformed digital asset integration. In the European Union, the Markets in Crypto-Assets (MiCA) regulation established a harmonized legal structure for crypto-asset service providers, token issuers, and stablecoin operators.
In the United States, regulatory approvals for spot exchange-traded products brought crypto custody and settlement under standard securities oversight.
These institutional structures require compliance with capital adequacy rules, anti-money laundering (AML) controls, and strict fiduciary risk standards.
When a macro shock occurs, an institutional desk governed by MiCA or SEC reporting mandates cannot casually “HODL” through deep drawdowns if their internal risk metrics mandate a balance sheet reduction.
Consequently, digital asset market liquidity now reflects the operational discipline of regulated financial institutions.
Corporate Treasuries and Sovereign Strategic Allocations
A growing roster of publicly traded enterprises and sovereign investment entities hold digital assets as strategic treasury reserves. These corporate holders face mark-to-market accounting standards and earnings scrutiny from Wall Street analysts.
When macroeconomic headwinds raise corporate borrowing costs or squeeze operating margins, corporate treasurers must evaluate their crypto positions through the lens of overall balance sheet health.
As a result, corporate treasury activity introduces traditional corporate finance realities directly into digital asset price formation.
Putting Frameworks into Action
Understanding these institutional mechanics is valuable, but how does an individual analyst or investment team synthesize these fifteen indicators into a cohesive, repeatable research process?
Practical Application: Building a Weekly Macro Research Routine
To avoid information overload, macro researchers should follow a structured, multi-tier analysis routine that separates daily noise from multi-month structural shifts.
- DXY & FX rates
- 10Y Nominal & TIPS Yields
- Spot ETF Net Flows
- Stablecoin Mint/Burn volumes
- Fed Net Liquidity changes
- High-Yield Credit Spreads
- ON RRP & TGA Balances
- CBOE VIX & Volatility Curves
- Global M2 Money Supply aggregates
- CPI & Core Inflation Reports
- Global Manufacturing PMI prints
- Central Bank Forward Guidance
Stage 1: The Daily Market Pulse (10 Minutes)
Begin each trading session by reviewing three high-frequency variables: the US Dollar Index (DXY), the 10-Year US Treasury yield, and spot ETF net inflows.
Check whether the dollar is breaking key technical resistance or support levels, examine if real yields are shifting, and inspect net institutional ETF subscriptions from the previous session.
This quick audit confirms whether the day’s market tone is characterized by risk-seeking or defensive behavior.
Stage 2: The Weekly Liquidity Audit (45 Minutes)
Every Thursday afternoon, the Federal Reserve updates its balance sheet balance via the H.4.1 statistical release.
Use this data to calculate the updated Federal Reserve Net Liquidity figure by subtracting current TGA and ON RRP balances from total Fed assets.
Next, inspect corporate credit spreads on platforms like the Federal Reserve Bank of St. Louis (FRED) to verify that high-yield debt spreads are not widening. Finally, check aggregate stablecoin supplies to confirm whether fresh fiat is minting onto distributed ledgers.
Stage 3: The Monthly Macro Synthesis (2 Hours)
Once a month, step back to analyze broad structural trends. Calculate the 3-month rolling growth rate of Global M2 money supply across the major central banks.
Review the latest CPI releases to evaluate the progress of disinflation, and examine whether the global manufacturing PMI is holding above or slipping below the 50 expansion marker.
Synthesizing these long-term indicators reveals whether the global economy is in a phase of monetary expansion, disinflationary growth, stagflation, or outright contraction.
Comparing Analytical Approaches
Now that we have established an actionable research routine, let us examine how these macroeconomic gauges contrast with traditional crypto-native on-chain metrics.
Traditional Metrics Versus Crypto-Native Indicators
A balanced crypto research framework does not choose between macro indicators and crypto-native metrics; it combines both to form a complete market view. Macro indicators measure the external supply of capital, while on-chain metrics evaluate the internal health of the network.
Consider a market environment where on-chain metrics like the Market Value to Realized Value (MVRV) ratio or network transaction counts show historically undervalued readings.
If macroeconomic indicators reveal that global M2 is contracting, real yields are pushing upward, and credit spreads are widening, an investor who relies solely on on-chain data will likely step in too early. The external capital necessary to fuel a recovery simply does not exist yet.
Conversely, when macro liquidity indicators begin to surge, on-chain metrics help investors identify which digital assets are experiencing genuine user adoption and network activity.
Macro indicators tell you when the tide is turning; on-chain metrics tell you which vessels are built to sail fastest. Integrating both disciplines shields research teams from common market blind spots.
Preparing for the Decade Ahead
As financial markets evolve, the relationship between digital assets and traditional macro indicators continues to mature, pointing toward a more sophisticated future.
The Next Evolution of Digital Asset Macroeconomics
The coming decade will see the boundaries between traditional financial plumbing and distributed blockchain ledgers blur even further. As real-world asset (RWA) tokenization expands, sovereign debt instruments, private credit facilities, and commercial paper will trade and settle natively on public and permissioned blockchains.
This financial convergence means that macro indicators will increasingly be measured on-chain in real time. Instead of waiting for weekly central bank reports or monthly government surveys, analysts will monitor tokenized treasury bill trading velocities, automated decentralized money market lending rates, and real-time cross-border stablecoin settlements.
Understanding the fifteen foundational macroeconomic indicators outlined in this guide provides the core knowledge required to navigate this integrated financial future.
Frequently Asked Questions
Which single macro indicator has the highest historical correlation with crypto?
Historically, Global M2 Money Supply (with an approximate 8 to 12-week lag) and Federal Reserve Net Liquidity exhibit the strongest, most consistent positive correlations with broad digital asset market cycles.
When fiat liquidity expands across the major world economies, digital assets absorb the surplus capital rapidly.
How does a change in the Federal Reserve’s policy rate impact altcoins compared to Bitcoin?
Central bank interest rate increases disproportionately impact altcoins compared to Bitcoin.
Because altcoins sit further out on the risk curve and often lack the established institutional custody infrastructure and liquidity of Bitcoin, investors aggressively liquidate lower-cap speculative tokens during monetary tightening cycles to preserve cash or consolidate into Bitcoin.
Why does Bitcoin sometimes trade like a tech stock and other times like digital gold?
Bitcoin exhibits dual characteristics depending on the specific nature of market stress.
During standard interest rate and liquidity cycles driven by growth and corporate earnings revisions, Bitcoin trades primarily as a high-beta technology asset correlated with the Nasdaq 100.
However, during acute confidence crises within the traditional banking system or periods of rapid sovereign currency depreciation, Bitcoin frequently decouples from tech equities and trades as an independent, non-sovereign monetary alternative, moving more closely in tandem with physical gold.
Can on-chain indicators override negative macroeconomic conditions?
No, on-chain indicators cannot sustainably override severe negative macroeconomic conditions over extended horizons.
While strong on-chain network growth or token supply burns can generate localized, short-term price rallies, an overarching contraction in global liquidity eventually limits the total capital available to support asset valuations.
Where can individual investors track these 15 macro indicators for free?
Investors can monitor these fifteen indicators across several reliable, accessible platforms.
The Federal Reserve Bank of St. Louis provides the FRED database, which covers Treasury yields, CPI, credit spreads, and central bank assets for free. The financial analytics portal MacroMicro offers dedicated dashboards comparing Bitcoin directly against global money supply and the US Dollar Index.
Cryptocurrency ETF flows and stablecoin capitalizations can be tracked on dedicated tracking sites like CoinGlass and DefiLlama.
ZenvestAI View
Macroeconomic research in crypto is often misunderstood as an attempt to predict the exact date and hour of every market turn. In reality, sound macro analysis is about understanding probabilities and market positioning.
Our research at ZenvestAI demonstrates that sustainable crypto market performance occurs when global liquidity expansion coincides with constructive on-chain fundamentals. By tracking these fifteen macro indicators with discipline, researchers transform confusing market volatility into clear, actionable structural trends.
The Bottom Line
Digital assets do not move in a financial vacuum; they are high-beta reflections of worldwide monetary liquidity and investor risk appetite.
Before analyzing individual token whitepapers or on-chain transaction volumes, first identify whether global central banks are expanding or contracting the supply of money. Master the macro environment, and you will navigate crypto market cycles with precision and confidence.
Related Intelligence
- The Federal Reserve Balance Sheet Decoded: Understanding Treasury General Account flows, repo mechanics, and their direct relationship to asset valuations.
- Stablecoins as the Sovereign Bridge: How tokenized fiat currencies alter foreign exchange dynamics and cross-border settlement.
- On-Chain Fundamentals vs. Macro Tides: A step-by-step methodology for pairing blockchain network metrics with global economic cycles.
Author and Editorial Information
Publisher: ZenvestAI Research Team
Lead Desk: Macro & Digital Asset Strategy
Division: Original Research & Institutional Analytics
This research is prepared for educational and analytical purposes, focusing on macroeconomic indicators, monetary conditions, global liquidity, financial markets, and their relevance to digital-asset research.
Research Contact: research@zenvestai.com
Regulatory Compliance and Analytical Disclosure:
This guide is prepared solely for informational and educational purposes in accordance with international financial education standards, including guidance published by the International Organization of Securities Commissions (IOSCO), the US Securities and Exchange Commission (SEC), and the European Union’s Markets in Crypto-Assets (MiCA) regulation. Nothing contained within this article constitutes financial, investment, legal, tax, or credit advice. Digital assets are subject to substantial market risks, price volatility, and regulatory developments. Past historical correlation between macroeconomic indicators and digital asset prices is no guarantee of future results. Always conduct independent research and consult certified professional advisors before making financial capital commitments.
