Millions of Indian retail traders wake up every morning wondering if their favorite cryptocurrency exchange will still work by dinner time, or if a sudden bank account freeze will lock up their hard-earned savings. This daily anxiety exists because crypto trading regulation in India is a real-world puzzle where the government collects a massive 30% flat tax on your digital profits while still refusing to pass a single, comprehensive cryptocurrency law.
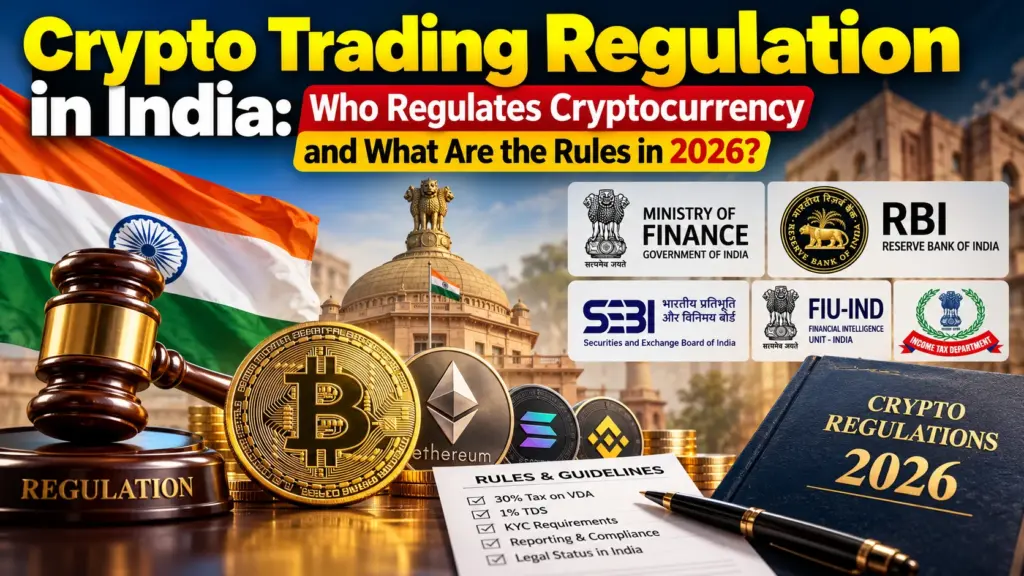
Instead of handing the keys to one boss, New Delhi has split cryptocurrency oversight across four powerful government watchdogs that monitor your money, your identity, and your taxes at the exact same time.
This guide explains the exact 2026 Indian crypto rulebook. It will show you who actually regulates what, whether your daily trading is legal, how the Financial Intelligence Unit (FIU-IND) polices global exchanges, and how to protect your net returns from brutal tax penalties.
ZenvestAI Explains: The Multi-Regulator Reality
India does not have a single cryptocurrency regulator in 2026. Cryptocurrency and Virtual Digital Assets (VDAs) remain broadly unregulated as traditional financial products. It means there is no single government license that turns a crypto exchange into a guaranteed, consumer-protected bank.
Instead, specific crypto activities fall under separate, strict legal frameworks: FIU-IND polices anti-money laundering (AML) and counter-terrorist financing (CFT) under the Prevention of Money Laundering Act (PMLA), while the Income Tax Department enforces the VDA tax framework under the Income-tax Act, 1961.
Before we examine each agency one by one, let us lock in the essential facts you need to remember today.
Key Takeaways
- Trading Is Legal, Spending Is Not: Buying, selling, and holding Virtual Digital Assets (VDAs) is completely legal in India, but crypto is not legal tender (you cannot force a merchant to accept Bitcoin like the Indian Rupee).
- No Single Watchdog Exists: Unlike the US SEC or the European Union’s MiCA framework, India divides crypto oversight among FIU-IND, the Income Tax Department (CBDT), the RBI, SEBI, and CERT-In.
- Mandatory FIU-IND Registration: Every domestic and offshore crypto exchange serving Indian users must register as a Reporting Entity with FIU-IND and conduct strict KYC verification.
- Heavy Tax Drag: All crypto profits face a flat 30% tax (plus 4% health and education cess) under Section 115BBH, alongside a 1% Tax Deducted at Source (TDS) under Section 194S with zero loss-offsetting allowed.
Seeing how these pieces fit together is much easier when you view the entire government structure side by side.
At a Glance: Who Regulates What in India’s Crypto Market (2026)
Every Indian government body touches a different part of your cryptocurrency journey, from the moment you deposit rupees to the day you file your tax return.
| Government Authority | Primary Role in Crypto (2026) | Legal Framework Used | What They Actually Control |
| FIU-IND (Financial Intelligence Unit) | AML / CFT Enforcement | Prevention of Money Laundering Act (PMLA, 2002) | Registers Indian and offshore VDA Service Providers, mandates KYC, tracks suspicious transactions, blocks non-compliant exchanges. |
| Income Tax Department (CBDT) | Tax Administration | Income-tax Act, 1961 (Sections 2(47A), 115BBH, 194S) | Collects 30% flat tax on VDA gains, enforces 1% TDS on trades, audits Schedule VDA in tax filings. |
| RBI (Reserve Bank of India) | Monetary Policy & Banking | RBI Act, 1934 & FEMA, 1999 | Oversees banking channels (UPI/IMPS/NEFT), monitors cross-border outflows, promotes the e-Rupee (CBDC). |
| SEBI (Securities and Exchange Board) | Securities Market Watchdog | SEBI Act, 1992 | Monitors tokenized securities and unauthorized investment schemes; awaits formal classification of VDAs. |
| CERT-In | Cybersecurity Standards | Information Technology Act, 2000 | Mandates 6-hour cyber incident reporting and 5-year log retention for all crypto platforms. |
| Ministry of Corporate Affairs (MCA) | Corporate Disclosure | Companies Act, 2013 (Schedule III) | Requires registered Indian companies to declare all VDA holdings and profits/losses in balance sheets. |
Table of Contents
- ZenvestAI Explains: The Multi-Regulator Reality
- Key Takeaways
- At a Glance: Who Regulates What in India’s Crypto Market (2026)
- What Is Crypto Trading Regulation in India and Is Crypto Legal?
- History: How India Moved From Banking Bans to Tax and AML Tracking
- How It Works: Why “Who Regulates What” Matters More Than Ever
- Core Components: Breaking Down the Four Pillars of Indian Crypto Oversight
- Important Types: Indian Exchanges vs. Offshore Exchanges vs. Self-Custody
- What Is Permitted vs. Restricted in 2026?
- Benefits of India’s Current Regulatory Framework
- Risks: Theory vs. Real-World Failure in Unprotected Markets
- How To Get Started Compliantly in 2026
- Security, PMLA, and KYC Requirements: What Exchanges Must Track
- Costs and Taxation: How Is Crypto Trading Taxed in India?
- Regulation in Global Context: How India Compares Worldwide
- Advanced Concepts: DeFi Liquidity Pools, AMM Math, and the 1% TDS Trap
- Common Mistakes Indian Crypto Traders Make in 2026
- Related Concepts Worth Exploring
- Glossary of Indian Crypto Regulatory Terms
- Frequently Asked Questions (FAQ)
- ZenvestAI View
- Official Sources & Verified Regulatory References
- Author, Editorial Information & Global Regulatory Disclosure
- Global Regulatory & Educational Disclosure (IOSCO / US SEC / EU MiCA / Indian Regulatory Compliance):
Now that you can see the full scoreboard of Indian regulators, we need to answer the foundational question every newcomer asks first.
What Is Crypto Trading Regulation in India and Is Crypto Legal?
Crypto trading regulation in India is a functional compliance system rather than a single rulebook. Yes, cryptocurrency trading is 100% legal in India in 2026.
Indian citizens are legally free to buy, sell, swap, and hold cryptocurrencies like Bitcoin (BTC), Ethereum (ETH), and Solana (SOL) using registered exchanges or personal self-custody hardware wallets.
However, Indian law draws a sharp, bright line between a legal asset and legal tender.
Under Indian law, only the Indian Rupee (INR) including the physical rupee and the RBI’s digital e-Rupee (CBDC) is recognized as official currency.
Instead of calling crypto “money,” the Indian government legally classifies all cryptocurrencies, non-fungible tokens (NFTs), and utility tokens as Virtual Digital Assets (VDAs) under Section 2(47A) of the Income-tax Act, 1961.
To understand why the government chose to tax and track crypto as an asset rather than ban it outright, it helps to look at the dramatic timeline that brought us to 2026.
History: How India Moved From Banking Bans to Tax and AML Tracking
India’s regulatory journey with digital assets has swung from aggressive hostility to structured surveillance over the past decade.
- April 2018 (The RBI Banking Ban): The Reserve Bank of India (RBI) issued a circular prohibiting all regulated Indian banks from providing services to crypto businesses, choking off rupee deposits.
- March 2020 (Supreme Court Victory): In the landmark Internet and Mobile Association of India (IAMAI) vs. RBI case, the Supreme Court of India struck down the 2018 banking ban as unconstitutional, reopening legal crypto trading across the country.
- April 2022 (The VDA Tax Era Begins): Through the Finance Act, 2022, the Ministry of Finance formally defined Virtual Digital Assets (VDAs) and introduced the 30% flat tax alongside the 1% TDS rule starting July 2022.
- March 2023 (PMLA Notification): The Ministry of Finance brought all crypto exchanges, custodians, and wallet providers under the Prevention of Money Laundering Act (PMLA), putting FIU-IND in charge of compliance.
- December 2023 – 2025 (Offshore Crackdown & Penalties): FIU-IND issued show-cause notices and blocked access to nine major offshore exchanges for operating illegally without registration. Major global platforms like Binance paid heavy financial penalties (such as an INR 18.82 crore / ~$2.25 million fine in 2024) to register as compliant Indian reporting entities.
- 2026 (Tightened PMLA & Global Alignment): While the Department of Economic Affairs (DEA) continues evaluating long-term legislative proposals (often discussed alongside the G20/FSB synthesis framework and draft COINS Bill concepts), PMLA amendments in 2026 have further tightened KYC and beneficial ownership reporting down to a 10% threshold.
Because history left India without a single crypto ministry, you might wonder how day-to-day oversight actually works behind the scenes.
How It Works: Why “Who Regulates What” Matters More Than Ever
India regulates cryptocurrency by tracking activity rather than issuing a blanket product stamp of approval.
When a public government statement says that crypto remains “unregulated” in India, it means that no authority guarantees the value of your token or steps in to bail you out if a speculative coin drops to zero.
At the exact same time, the act of moving money into an exchange, verifying your identity, executing a trade, and booking a profit is heavily policed.
If you mistakenly believe that “no single crypto bill” means “no rules apply,” you can accidentally trigger anti-money laundering alerts or income tax evasion notices.
To stay safe, every Indian trader needs to examine the four core government pillars that control these daily activities.
Core Components: Breaking Down the Four Pillars of Indian Crypto Oversight
Each major Indian institution answers a different piece of the regulatory puzzle.
1. Does RBI Regulate Crypto? (Banking Channels & Macro Stability)
The Reserve Bank of India (RBI) does not directly regulate spot cryptocurrency trading or register crypto exchanges.
Instead, the RBI regulates the Indian banking system, payment gateways (like UPI, IMPS, and NEFT), and cross-border currency flows under the Foreign Exchange Management Act (FEMA, 1999).
Under Governor Sanjay Malhotra in 2026, the RBI maintains deep institutional caution toward private cryptocurrencies, viewing unbacked digital tokens as a threat to macroeconomic and financial stability while actively promoting the sovereign e-Rupee (Central Bank Digital Currency).
While the RBI cannot ban banks from serving legitimate crypto traders due to the 2020 Supreme Court ruling, banks still run strict fraud and FEMA checks meaning sending Indian rupees abroad to buy crypto on unauthorized offshore platforms can violate foreign exchange rules.
2. Does SEBI Regulate Crypto? (Securities vs. Virtual Digital Assets)
The Securities and Exchange Board of India (SEBI) does not currently regulate standard cryptocurrencies like Bitcoin or Ethereum, nor has it authorized any domestic crypto ETFs or crypto-linked mutual funds in India.
SEBI awaits a formal parliamentary law before asserting direct jurisdiction over Virtual Digital Assets that behave like investment contracts.
However, if a company uses blockchain tokenization to raise public capital in a way that mimics an unlicensed stock offering (an illegal Collective Investment Scheme), SEBI has the legal teeth to step in and shut it down.
3. What Does FIU-IND Regulate? (The Frontline PMLA Watchdog)
The Financial Intelligence Unit – India (FIU-IND), operating under the Ministry of Finance, is the most active day-to-day supervisor of crypto platforms in India.
Under the March 2023 PMLA notification and subsequent 2026 PMLA updates, any business that exchanges between VDAs and fiat currencies, swaps one VDA for another, transfers VDAs, or safekeeps digital assets must register with FIU-IND as a Reporting Entity.
Crucially, FIU-IND registration is not a financial license.
As government disclosures via the Press Information Bureau (PIB) consistently emphasize, FIU-IND registration only enforces anti-money laundering (AML) and counter-terrorist financing (CFT) tracking; it does not guarantee the financial safety or solvency of an exchange.
4. What Role Does the Income Tax Department Play? (CBDT & VDA Taxes)
The Income Tax Department, governed by the Central Board of Direct Taxes (CBDT), administers the entire VDA tax framework.
It does not care whether your token is a utility coin, a meme coin, or a governance token; if you transfer a VDA and make a profit, the Income Tax Department collects its statutory share through automated exchange reporting (Form 26AS and the Annual Information Statement - AIS) and dedicated tax return tables (Schedule VDA).
Knowing who watches your trades naturally raises the next practical question: how do these agencies treat the specific exchange apps you actually use on your phone?
Important Types: Indian Exchanges vs. Offshore Exchanges vs. Self-Custody
The rules that apply to your trading depend heavily on where your trades take place.
- FIU-Registered Indian Exchanges (e.g., CoinDCX, Mudrex, ZebPay, CoinSwitch, Giottus): These domestic platforms are registered in India with FIU-IND. They automatically deduct 1% TDS on your trades, file reports directly linked to your PAN card, and support direct INR deposits and withdrawals under strict bank monitoring.
- FIU-Registered Offshore Exchanges (e.g., Binance, KuCoin): Global platforms that have completed FIU-IND registration and paid historical compliance fines are legally accessible in India without URL blocks. However, setting up and securing a Binance account in India requires full Indian KYC, and traders must pay close attention to whether the platform automatically deducts the 1% Indian TDS or leaves the quarterly tax-filing burden on the individual user.
- Unregistered Offshore Exchanges: Global offshore crypto exchanges that refuse to register with FIU-IND are deemed illegal under the PMLA. Their websites and mobile apps are routinely blocked by the Ministry of Electronics and Information Technology (MeitY) under Section 69A of the Information Technology Act.
- Self-Custody Hardware Wallets (e.g., Ledger, Trezor): Holding your own private keys on a cold storage hardware wallet is completely legal in India. However, moving crypto between an Indian exchange and your personal hardware wallet requires wallet address verification (“whitelisting”) under FIU-IND Travel Rule guidelines.
Seeing how different platforms operate helps clarify what kinds of crypto activities are actually allowed across the country today.
What Is Permitted vs. Restricted in 2026?
Indian traders can engage in several blockchain activities, provided they stay within the boundaries of tax and foreign exchange laws.
- Spot Buying, Selling, and Holding (Permitted): Purchasing Bitcoin or altcoins with INR on an FIU-registered exchange and holding them long-term is fully permitted.
- Crypto-to-Crypto Swaps (Permitted & Taxed): Trading stablecoins like USDT for BTC or swapping ETH for SOL is legal, though every single swap counts as a taxable transfer.
- Crypto Derivatives & Futures (Permitted with Caveats): Many Indian and FIU-registered platforms offer INR-settled or USDT-margined futures contracts. While crypto futures trading is legal on compliant platforms, its tax treatment requires strict classification under Section 115BBH or business income rules—consult a chartered accountant before scaling leverage.
- Everyday Retail Payments (Restricted as Legal Tender): Because crypto is not legal tender, it cannot replace the Rupee as an official currency for domestic commerce.
- Cross-Border Forex Bypass (Prohibited under FEMA): Using cryptocurrency or stablecoins like USDT to illegally move wealth out of India outside the RBI’s Liberalised Remittance Scheme (LRS) is a serious violation of FEMA.
Even with strict boundaries, this structured tracking system offers clear advantages for serious market participants.
Benefits of India’s Current Regulatory Framework
While traders often complain about high taxes, the 2026 compliance structure provides concrete stability compared to the chaotic banking bans of the past.
- Elimination of Outright Ban Fears: With the government collecting thousands of crores in 1% TDS and 30% VDA tax while integrating exchanges into the PMLA, crypto is deeply embedded in India’s tax reporting machinery.
- Cleaner Institutional KYC Standards: Mandatory FIU-IND oversight forces exchanges to verify identities, reducing the risk of illicit darknet funds mixing with retail order books.
- Clear Audit Trails via AIS: Automatic reflection of 1% TDS in your Annual Information Statement (AIS) gives honest traders a documented paper trail to show banks where their wealth originated.
However, having a tax trail does not mean the government protects your capital when things go wrong—which brings us to the severe real-world risks every trader must confront.
Risks: Theory vs. Real-World Failure in Unprotected Markets
In theory, registering with a government body sounds like a safety guarantee; in practice, FIU-IND registration provides zero consumer insurance.
- Exchange Hacks and Locked Withdrawals (Real-World Failure): When major Indian platform WazirX suffered a catastrophic $230 million+ (~INR 1,900+ crore) multi-signature wallet exploit in July 2024, millions of Indian users saw their portfolios frozen in lengthy restructuring disputes. Neither the RBI, SEBI, nor the Deposit Insurance and Credit Guarantee Corporation (DICGC) stepped in to refund users, because crypto exchanges are not regulated banks or stockbrokers.
- P2P Bank Account Freezes (Real-World Failure): Peer-to-peer (P2P) trading—where buyers send INR directly to a seller’s bank account via UPI or IMPS in exchange for USDT—has triggered tens of thousands of cybercrime bank freezes across India. If a scammer uses stolen funds to buy USDT from an innocent P2P seller, the National Cyber Crime Reporting Portal (NCRP) traces the tainted rupee trail and places a lien or full freeze on the innocent seller’s bank account.
Understanding these hard truths makes it much easier to set up a safe, compliant trading workflow from day one.
How To Get Started Compliantly in 2026
Following five strict rules keeps your trading account legal and your bank account safe from cybercrime liens.
- Verify the FIU-IND Registration List: Only create accounts on exchanges officially registered as VDA Reporting Entities with FIU-IND.
- Complete Full PAN and Aadhaar KYC: Link your valid Permanent Account Number (PAN), complete Aadhaar OTP verification, and submit a live selfie so your tax credits map accurately to your Form 26AS.
- Use Direct Bank Transfers Over P2P: Deposit and withdraw Indian Rupees directly between your verified bank account and the exchange’s corporate banking partner rather than accepting unknown third-party P2P UPI transfers.
- Move Long-Term Holdings to Self-Custody: Do not leave life-changing capital sitting on an exchange hot wallet; withdraw long-term holdings to a personal hardware wallet (like a Ledger or Trezor) after understanding how a crypto wallet works and completing the exchange’s self-custody ownership verification.
- Download Monthly Trade Ledgers: Export your CSV trade history at the end of every month so you are never caught off-guard during the July 31 ITR filing deadline on the Income Tax e-Filing Portal.
Once your trading workflow is running, you will quickly notice the rigorous identity and cybersecurity checks that platforms now enforce under the law.
Security, PMLA, and KYC Requirements: What Exchanges Must Track
Under the Prevention of Money Laundering Act (PMLA, 2002) including the October 2026 PMLA rules amendments and the 2022 CERT-In Cybersecurity Directions, every compliant exchange operating in India must enforce strict surveillance protocols:
- Enhanced Client Due Diligence (KYC): Platforms must verify your PAN, Aadhaar, bank account ownership (via penny-drop verification), live facial biometrics, and geographical IP address. Under 2026 PMLA updates, corporate entities trading VDAs must also disclose beneficial ownership for anyone holding 10% or more control, along with registered office and primary business address proof.
- Suspicious Transaction Reports (STRs): Exchanges must appoint a Principal Officer who reports suspicious volume spikes, rapid wash trading, or transfers linked to flagged wallets directly to FIU-IND.
- 5-Year Record Retention: Both PMLA and CERT-In rules force exchanges to maintain full transaction histories, KYC records, and IP logs for at least five years even after you close your account.
- 6-Hour Cyber Incident Reporting: Under CERT-In mandates, any exchange suffering a smart contract breach, unauthorized wallet drain, or server hack must report the incident to the government within six hours.
While security rules protect the financial system, the rules that directly reduce your personal wallet balance are the tax laws—and getting the math wrong can wipe out your capital.
Costs and Taxation: How Is Crypto Trading Taxed in India?
India operates one of the world’s strictest cryptocurrency tax regimes under Section 115BBH and Section 194S of the Income-tax Act, 1961. Here are the four non-negotiable tax rules for FY 2026–27:
- Flat 30% Tax + 4% Cess (31.2% Effective Rate): Every profitable crypto sale or crypto-to-crypto swap is taxed at a flat 30% (plus 4% health and education cess, bringing the minimum effective rate to 31.2%, plus applicable surcharges for high earners), regardless of your personal income tax slab or whether you held the coin for ten minutes or ten years.
- Zero Deduction for Expenses: When calculating your taxable profit, you are only allowed to deduct the Cost of Acquisition (purchase price). You cannot deduct exchange trading fees, blockchain gas fees, internet bills, or staking hardware costs.
- No Loss Offset Allowed: You cannot offset a loss from one cryptocurrency against a profit in another cryptocurrency. Nor can you carry forward crypto losses to future tax years.
- 1% TDS on Every Sell/Swap (Section 194S): A 1% Tax Deducted at Source (TDS) is deducted on the gross sale value of every VDA transaction once your annual trading volume crosses INR 50,000 (for “Specified Persons,” which covers most retail individuals without business tax audits) or INR 10,000 (for standard categories).
Separating Gross Profit From Net Reality
Many retail traders believe that breaking even across two trades means they owe zero tax—a misconception that leads to devastating tax bills. Let us verify the exact mathematics using a $2,000 USD (~INR 1,68,000) two-trade portfolio scenario:
- Trade 1 (Bitcoin Winner): You buy $1,000 (INR 84,000) of BTC and sell it for $1,500 (INR 1,26,000) (ignoring exchange fees, which are non-deductible).
- Gross Profit on BTC: $1,500 − $1,000 = $500 (INR 42,000).
- Trade 2 (Ethereum Loser): You buy $1,000 (INR 84,000) of ETH and sell it at a loss for $500 (INR 42,000).
- Gross Loss on ETH: $500 − $1,000 = −$500 (−INR 42,000).
What Is Your Actual Net Portfolio Profit?
Net Economic Profit = +$500 (BTC Gain) − $500 (ETH Loss) = $0 (INR 0)
What Does the Indian Income Tax Department Demand Under Section 115BBH? Because loss-offsetting is strictly banned, the tax engine ignores your $500 ETH loss completely and taxes your $500 BTC gain in isolation:
- Taxable VDA Income = $500 (INR 42,000)
- Base Tax (30%) = $500 × 0.30 = $150 (INR 12,600)
- Cess (4% on Tax) = $150 × 0.04 = $6 (INR 504)
- Total Tax Payable (31.2%) = $156 (INR 13,104)
Additionally, when you executed those two sales totaling $2,000 ($1,500 BTC sale + $500 ETH sale), the exchange deducted 1% TDS on the gross sale value:
- 1% TDS Deducted at Source = $2,000 × 0.01 = $20 (INR 1,680)
(Note: That $20 TDS is credited in your Form 26AS, meaning you pay the remaining $156 − $20 = $136 when filing your ITR-2 or ITR-3 via Schedule VDA). Even though you made $0 in real life, your net post-tax reality is a -$156 (-INR 13,104) capital loss, even before counting exchange fees and gas slippage.
ZenvestAI Indian Crypto Tax Reality Calculator — 2026
Scenario calculator for Section 115BBH, Section 194S TDS and the economic impact of non-offsettable VDA losses.
Seeing how aggressive India’s domestic tax math is begs a global comparison: how does India stack up against the rest of the world in 2026?
Regulation in Global Context: How India Compares Worldwide
To understand where India’s regulatory architecture stands, it helps to compare New Delhi’s approach with the future of global crypto regulations across major financial hubs in 2026.
- European Union (MiCA Framework): Fully operational across the EU since late 2024, Markets in Crypto-Assets (MiCA) provides a single, unified licensing passport for crypto exchanges and strict reserve rules for stablecoins—giving European retail traders formal consumer protection that India currently lacks.
- United States (SEC / CFTC & Spot ETFs): The US regulates crypto through SEC securities and CFTC commodities enforcement alongside approved Spot Bitcoin and Ethereum ETFs, allowing American investors to trade crypto inside regulated brokerage accounts and offset capital losses against capital gains.
- UAE (VARA in Dubai & ADGM): The United Arab Emirates operates a dedicated, specialized virtual asset regulator (VARA) with 0% personal capital gains tax for individual traders, drawing thousands of Indian Web3 founders and high-frequency traders to Dubai.
- India (Multi-Agency Tax & AML Model): India stands out as a high-tax, strict-AML jurisdiction that prioritizes fiscal revenue (30% tax / 1% TDS) and financial surveillance (FIU-IND) while withholding formal financial product licensing.
For advanced traders who go beyond simple spot buying and use decentralized protocols, this Indian regulatory model creates unique mathematical friction.
Advanced Concepts: DeFi Liquidity Pools, AMM Math, and the 1% TDS Trap
When experienced Indian traders move on-chain to use Automated Market Makers (AMMs) like Uniswap or Raydium, domestic tax rules collide directly with decentralized finance (DeFi) mechanics in India.
Every time you provide liquidity to a decentralized pool, the AMM prices assets using the constant-product formula:
x × y = k
Where x is the reserve of Token A, y is the reserve of Token B, and k is a constant invariant.
Let us verify the exact constant-product math to see how divergence loss (impermanent loss) interacts with Indian tax rules:
- Suppose you deposit 1 ETH (worth $2,000) and 2,000 USDT into a 50/50 AMM pool (Total initial value = $4,000).
- Here, the constant product is: k = 1 × 2,000 = 2,000
- ETH price doubles to $4,000
- Now suppose the external market price of ETH doubles to $4,000. Arbitrage traders buy ETH from the pool and add USDT until the pool ratio matches the $4,000 price (y / x = 4,000) while keeping x × y = 2,000.
- New pool balances– Solving for the new pool balances:- x = √(2,000 ÷ 4,000) = √0.5 ≈ 0.7071 ETH, y = √(2,000 × 4,000) = √8,000,000 ≈ 2,828.43 USDT
- Gross Pool Value at Withdrawal:- (0.7071 ETH × $4,000) + 2,828.43 USDT = $5,656.85
- Value if You Had Simply Held (HODL):- (1 ETH × $4,000) + 2,000 USDT = $6,000.00
- Divergence Loss (Impermanent Loss) :- $6,000.00 − $5,656.85 = $343.15 (5.72% loss vs. HODLing)
The Indian Regulatory Trap on DeFi Yields: Even if an AMM protocol advertises a gross yield of 15% APY in trading fees, your net reality in India must subtract:
- The $343.15 divergence loss calculated above.
- Non-deductible blockchain gas fees (which Section 115BBH forbids you from subtracting).
- A potential 31.2% tax triggered the moment you swap your LP tokens back into base assets, plus 1% TDS compliance obligations on every on-chain swap.
Even traders who stay completely away from DeFi still lose money every year by falling into basic compliance traps.
Common Mistakes Indian Crypto Traders Make in 2026
Avoiding these four widespread errors will save you from tax notices and frozen bank accounts:
- Assuming Crypto-to-Crypto Swaps Are Tax-Free: Many traders think tax only applies when withdrawing INR to a bank account. In reality, swapping Bitcoin for USDT or USDT for Solana is a taxable transfer under Section 115BBH the second the swap executes.
- Thinking a VPN Hides Offshore Trades From the Taxman: Using a VPN to access an unregistered offshore exchange violates FIU-IND rules, and the moment you move funds back through an Indian bank or an FIU-registered bridge, on-chain blockchain analytics and AIS data flag the unreported origin.
- Skipping Schedule VDA Because You Made a Net Loss: Even if every trade you made in FY 2026–27 lost money, if 1% TDS was deducted and appears in your Form 26AS / AIS, failing to declare those transactions in Schedule VDA triggers an automated mismatch notice from the Income Tax Department.
- Selling USDT to Strangers on P2P for a Small Premium: Chasing an extra INR 1–2 per USDT on peer-to-peer marketplaces exposes your primary savings account to cybercrime freezes if the buyer sends you scammed funds.
Mastering these compliance rules works best when you also connect them to the broader financial concepts shaping the market.
Related Concepts Worth Exploring
To build a complete picture of how Indian crypto rules fit into the wider economy, keep these connected frameworks in mind:
- e-Rupee (Digital Rupee / CBDC): The RBI’s sovereign digital currency, which carries full legal tender status and zero 30% VDA tax, unlike private cryptocurrencies.
- Liberalised Remittance Scheme (LRS): The RBI framework governing how much foreign currency an Indian resident can legally remit abroad ($250,000 USD per financial year)—which strictly restricts unauthorized offshore crypto funding.
- FATF Travel Rule: The global Financial Action Task Force (FATF) standard enforced by FIU-IND that requires exchanges to share sender and receiver identity data for crypto transfers above specified thresholds.
- Crypto Accounting Schedule III: The Ministry of Corporate Affairs mandate requiring Indian companies to disclose VDA holdings in annual corporate filings.
Because regulatory discussions rely on precise legal codes, keep this quick glossary handy whenever you read a government circular.
Glossary of Indian Crypto Regulatory Terms
- VDA (Virtual Digital Asset): The official legal term under Section 2(47A) of the Income-tax Act, 1961 covering cryptocurrencies, NFTs, and specified digital tokens.
- FIU-IND (Financial Intelligence Unit – India): The national agency under the Ministry of Finance responsible for receiving, processing, and analyzing suspect financial transaction reports under the PMLA.
- PMLA (Prevention of Money Laundering Act, 2002): India’s primary anti-money laundering law, which legally classifies crypto exchanges as Reporting Entities.
- Section 115BBH: The section of the Income-tax Act that enforces a flat 30% tax on VDA gains and bans the offsetting of losses or deduction of fees.
- Section 194S: The section of the Income-tax Act that mandates a 1% Tax Deducted at Source (TDS) on the transfer of Virtual Digital Assets above statutory thresholds.
- Schedule VDA: The dedicated reporting table inside Indian Income Tax Return forms (ITR-2 and ITR-3) where every crypto trade must be itemized.
With the core laws, math, and terminology clear, let us answer the most specific questions Indian traders ask in 2026.
Frequently Asked Questions (FAQ)
What is crypto trading regulation in India in 2026?
Crypto trading regulation in India is a multi-agency compliance structure rather than a single crypto law. FIU-IND regulates exchanges for anti-money laundering and KYC compliance under the PMLA, the Income Tax Department taxes profits at 30% and collects 1% TDS, the RBI oversees banking channels, and CERT-In enforces cybersecurity logging.
Is holding Bitcoin or USDT in a personal hardware wallet legal in India?
Yes, self-custody is completely legal in India. You can hold Bitcoin, Ethereum, or stablecoins on hardware wallets like Ledger or Trezor without paying tax simply for holding; taxes only apply when you sell, swap, or transfer the asset for a gain.
Can I reduce my 30% crypto tax by deducting exchange trading fees or blockchain gas fees?
No. Under Section 115BBH of the Income-tax Act, the only deduction permitted when calculating your taxable VDA gain is the original Cost of Acquisition (purchase price). Exchange commissions, gas fees, and crypto staking hardware costs cannot be deducted.
How is cryptocurrency received as a gift or airdrop taxed in India?
Under Section 56(2)(x) of the Income-tax Act, if you receive cryptocurrency as a gift from a non-relative and the total fair market value exceeds INR 50,000 (~$600 USD) in a financial year, the entire value is taxed as “Income from Other Sources” at your regular income tax slab rate. When you later sell that gifted or airdropped token, any profit is taxed at the flat 30% VDA rate under Section 115BBH.
What happens if I trade on an offshore exchange that is not registered with FIU-IND?
Trading on an unregistered offshore exchange exposes you to sudden website/app blackouts ordered by MeitY, potential FEMA violations if you wire funds abroad illegally, and severe Income Tax penalties if you fail to self-deposit the mandatory 1% TDS under Section 194S.
ZenvestAI View
While almost every website on the internet simply repeats the headline “30% tax and 1% TDS,” ZenvestAI’s proprietary regulatory and quantitative modeling uncovers three structural truths about the 2026 Indian market that you will not find on standard portals:
- The “ZenvestAI Round-Trip Friction Index” (Why Scalping Breaks at 58% Win Rates): Standard financial articles analyze the 1% TDS and 31.2% effective tax separately. However, when ZenvestAI models an active Indian intraday trader executing 20 round-trip spot trades per month with an average gross profit target of 3% and a stop-loss of -2%, the ban on loss-offsetting under Section 115BBH creates a mathematical cliff. Even if a trader achieves a respectable 55% win rate (winning 11 trades of $100 each = +$1,100 gross win; losing 9 trades of -$100 each = -$900 gross loss, leaving a +$200 pre-tax profit), the Indian tax engine charges 31.2% on the $1,100 gross wins ($343.20 tax) while ignoring the -$900 losses. The trader finishes with a -$143.20 net loss despite being a profitable trader before tax. ZenvestAI Benchmark: Under current Indian tax law, a symmetric 1:1 risk-to-reward ratio strategy requires a minimum 59.2% win rate (before exchange fees) just to break even after taxes.
- The “Surveillance-Without-Solvency” Paradox: India has quietly built one of the world’s tightest identity tracking meshes—linking PAN, Aadhaar, AIS tax ledgers, 5-year CERT-In IP logs, and 2026 PMLA 10% beneficial ownership disclosures. Yet, zero statutory rules require Indian exchanges to publish cryptographic Proof-of-Reserves (PoR) audited by a central financial regulator or segregate customer assets under a statutory bankruptcy trust. In short, the state knows every rupee you deposit, but if an exchange mismanages custody, you are treated as an unsecured creditor.
- The Hidden Liquidity Drain of Section 194S on Market Makers: Because 1% TDS applies to the gross transaction value rather than net profit, high-frequency market makers cannot provide tight bid-ask spreads on domestic Indian order books without locking up 1% of their entire principal on every single turn of inventory. This explains why domestic INR order books often suffer wider slippage during volatile market crashes compared to global USDT order books, directly impacting cross-exchange arbitrage opportunities.
The Bottom Line:- Crypto Trading Regulation in India: Who Regulates Cryptocurrency and What Are the Rules in 2026?
After reading everything, the one thing you must understand is this: Cryptocurrency trading is completely legal in India in 2026. But, because oversight is split between FIU-IND (strict KYC/AML tracking) and the Income Tax Department (30% tax + 1% TDS with zero loss offsets) without a consumer-protection regulator like SEBI or RBI insuring your funds, your survival depends on trading only on FIU-registered exchanges, avoiding third-party P2P bank transfers, and calculating your post-tax math before every trade—whether you are dollar-cost averaging via Bitcoin SIPs or actively trading the market.
Official Sources & Verified Regulatory References
All statutory facts, tax rates, and regulatory roles in this guide are verified against official Government of India notifications and legal publications:
- Press Information Bureau (PIB), Ministry of Finance, Government of India: Official parliamentary responses clarifying the role of FIU-IND, the inclusion of VDA service providers under the PMLA (Notification S.O. 1072(E), March 7, 2023), and the taxation of Virtual Digital Assets — https://pib.gov.in
- Financial Intelligence Unit – India (FIU-IND): AML/CFT Guidelines for Reporting Entities Providing Services Related to Virtual Digital Assets & Registration Directives — https://fiuindia.gov.in
- Income Tax Department (Central Board of Direct Taxes – CBDT): Finance Act, 2022 & Income-tax Act, 1961 provisions for Section 2(47A) (Definition of VDA), Section 115BBH (30% Tax on VDA income), and Section 194S (1% TDS Guidelines) — https://incometaxindia.gov.in
- Indian Computer Emergency Response Team (CERT-In), MeitY: Cybersecurity Directions of April 28, 2022 under Section 70B(6) of the Information Technology Act, 2000 (6-hour incident reporting and 5-year KYC/log retention for VASPs) — https://www.cert-in.org.in
- Reserve Bank of India (RBI): Official notifications on Central Bank Digital Currency (e-Rupee) and FEMA, 1999 cross-border remittance regulations — https://www.rbi.org.in
Author, Editorial Information & Global Regulatory Disclosure
Published by: ZenvestAI Editorial & Regulatory Research Desk (ZenvestAI.com)
Editorial Standards: Written and verified under the ZenvestAI Layer-1 Accuracy & People-First Quality Framework. All mathematical scenarios and statutory citations are independently audited prior to publication.
Last Updated: October 2026
Global Regulatory & Educational Disclosure (IOSCO / US SEC / EU MiCA / Indian Regulatory Compliance):
This article is published by ZenvestAI (zenvestai.com) strictly for educational, informational, and general research purposes. In accordance with global regulatory standards—including principles established by the International Organization of Securities Commissions (IOSCO), the U.S. Securities and Exchange Commission (US SEC), the European Union’s Markets in Crypto-Assets (EU MiCA) regulation, and applicable Indian laws (SEBI, RBI, FIU-IND, and the Income-tax Act, 1961)—nothing in this publication constitutes financial advice, investment advice, trading advice, legal counsel, or tax advisory services. Virtual Digital Assets (VDAs) and cryptocurrencies are highly volatile, largely unregulated as financial products in India, and carry no statutory consumer protection or deposit insurance. Displayed protocol returns or gross trading gains do not account for divergence loss, blockchain gas fees, smart contract vulnerabilities, exchange custody failures, or India’s mandatory 30% tax and 1% TDS deductions. Readers should verify all rules against official government notifications and consult a qualified Chartered Accountant (CA) or legal professional before making any financial or tax decisions.